Republic Republic Republic
  • Log in
Open account
Oops! We couldn’t find any results...
Can’t find a deal? Try advanced search.
Is something missing? Add your suggestion here.
Live deals Investment opportunities Trading Buy and sell Republic Note Own a piece of Republic's upside
Republic Ventures Opportunities for accredited investors
Republic Capital Multi-stage venture firm
Wallet Manage your digital assets Mobile app Available on iOS or Android Learning center Explore investor resources FAQ Get your questions answered
Capital fundraising Raise on Republic Tokenized assets Design, launch, manage tokenized assets Sharedrops Gift equity as a reward Founder Academy A complete guide to raising funds
Advisory Access veteran web3 advisors Infrastructure Stake your digital assets Tokenization Deploy your assets on-chain
Republic Capital In-house Venture Capital fund Broker dealer Regulated capital services
Republic Republic Republic
Oops! We couldn’t find any results...
Can’t find a deal? Try advanced search.
Is something missing? Add your suggestion here.
  • US

  • Log in
  • Open account
All investors
Live deals Investment opportunities Trading Buy and sell
Republic Note Own a piece of Republic's upside
Accredited only
Republic Ventures Opportunities for accredited investors
Institutional
Republic Capital Multi-stage venture firm
More
Wallet Manage your digital assets Mobile app Available on iOS or Android Learning center Explore investor resources FAQ Get your questions answered
Spotlight deal
Grayscale DeFI Fund (Reg D)
Invests in the tokenized infrastructure of onchain finance
Growth capital solutions
Capital fundraising Raise on Republic Tokenized assets Design, launch, manage tokenized assets Sharedrops Gift equity as a reward Founder Academy A complete guide to raising funds
Web3 services
Advisory Access veteran web3 advisors Infrastructure Stake your digital assets
Tokenization Deploy your assets on-chain
Institutional services
Republic Capital In-house Venture Capital fund
Broker dealer Regulated capital services
Logo of IZOLA

IZOLA People drive hours for IZOLA. One profitable destination. Now building what comes next.

Special Software Women Founders Reduce, Reuse, Recycle Food B2C Security Social Justice
Facebook Telegram Twitter LinkedIn
Featured image of IZOLA
Special terms: $242,750 left
$7,250
9% raised of $75K min
3
Investors
361 days
Left to invest
Invest in IZOLA
$1,000 minimum investment · Deal terms
Pitch Discussion Updates Reviews 1
Invest Invest in IZOLA
Facebook Telegram Twitter LinkedIn
Investor Story Team Our Story The Product Social Proof IzOS Hospitality Placemaking Scaling Craft Izola Main Platform Economics Growth Plan Joy + Justice Use of Funds Investor Returns What's Next Financial Model
About Team Press FAQ Risks Discussion

Documents

Republic (OpenDeal Portal LLC, CRD #283874) is hosting this Reg CF securities offering by Tallgrass Pictures LLC. View the official SEC filing and all updates:
Official SEC Logo Form C SEC.gov
Company documents
Subscription Agreement IZOLA_Form C.pdf
Loading

Hear from some of the 3 investors in IZOLA


Show more

Highlights


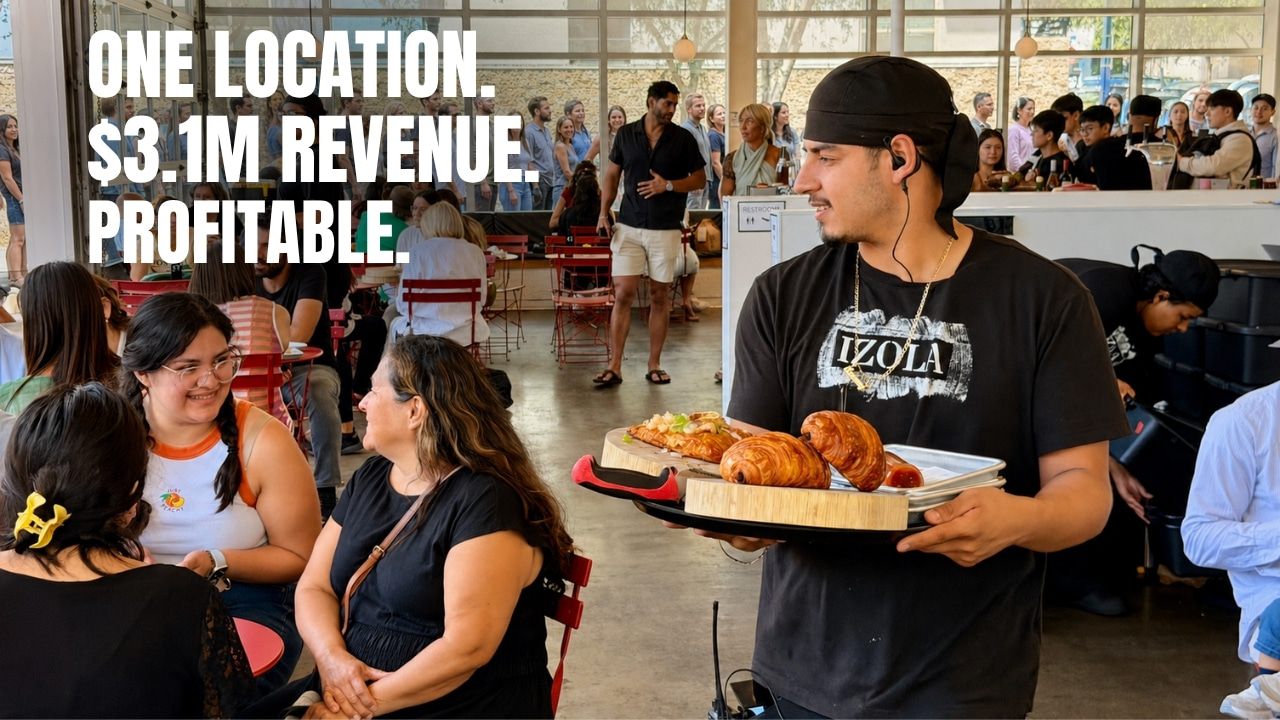
  • $3.1M audited revenue. $338K EBITDA. ~7× U.S. bakery average.
  • Location #2 opens Q4 2026, exceptional REIT-backed economics.
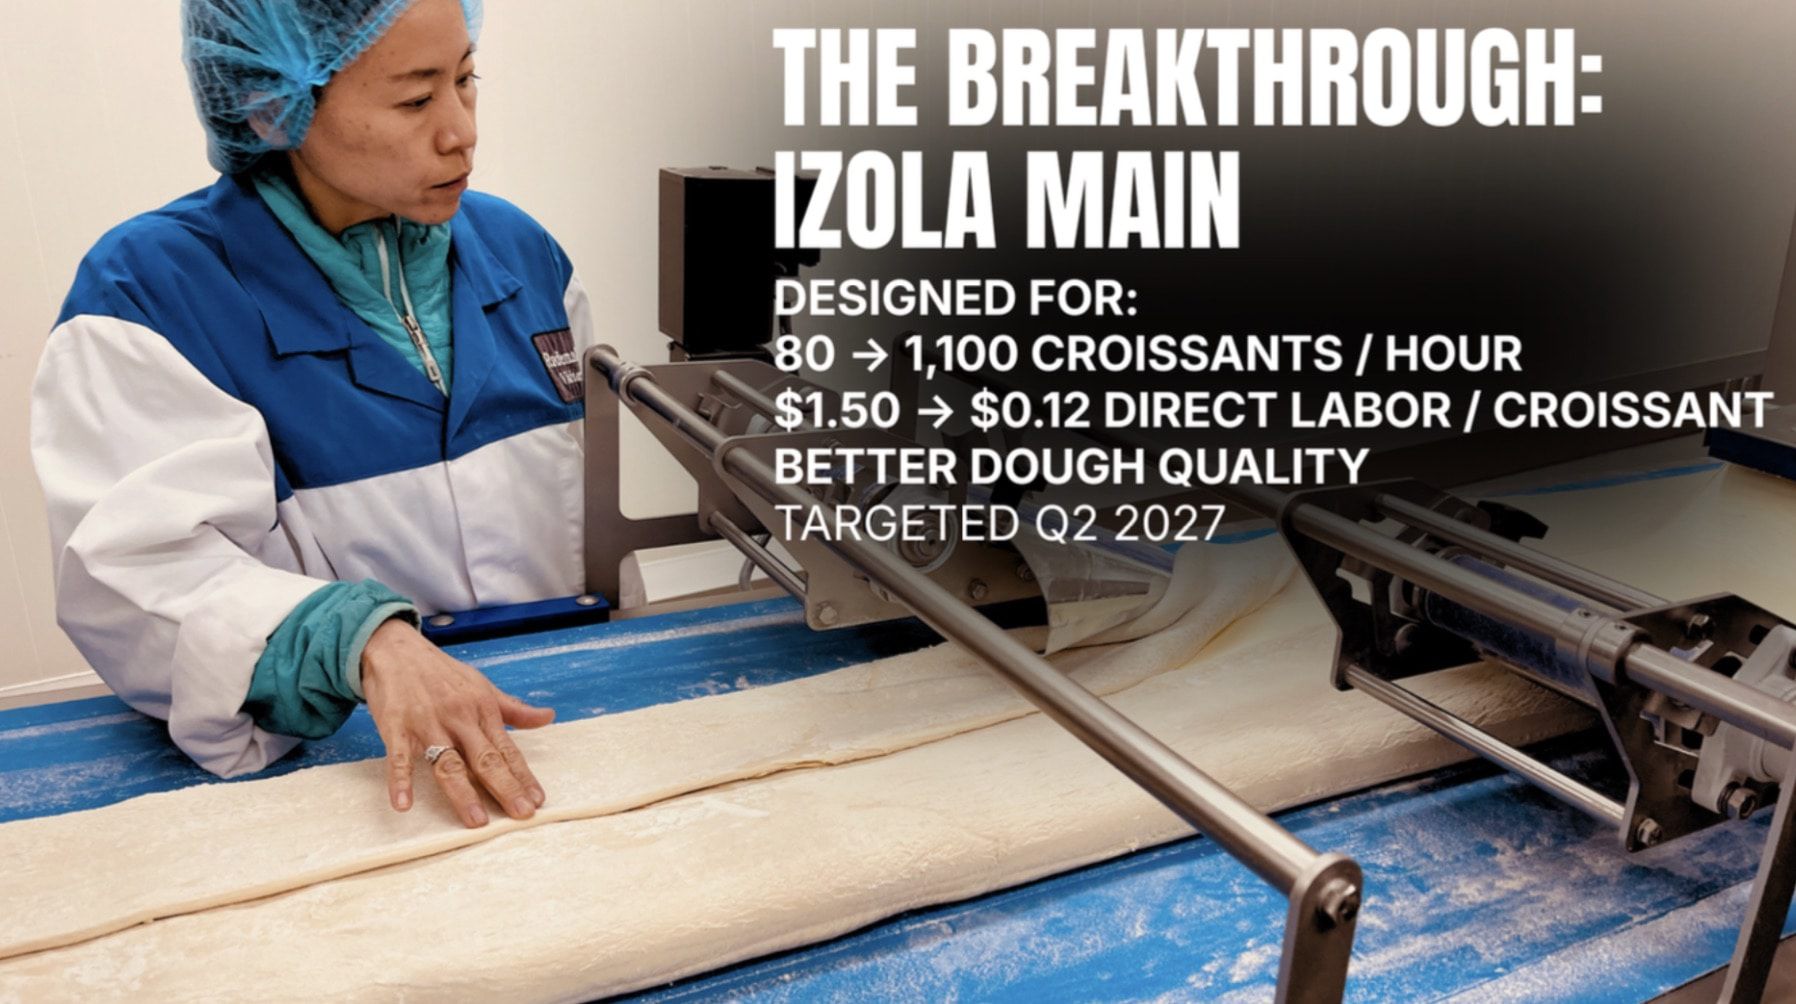
  • IZOLA Main: targets 13× output; 92% lower direct labor cost/croissant.
  • 2030 plan: 7 locations, $32.1M revenue, $9.3M mgmt EBITDA.
  • Yelp’s #1 U.S. bakery in 2022. 1,869 five-star Google reviews.
  • Fine-dining care at scale: 400 orders in 6 hrs; 1,000+ peak guests.
  • 796 investors. $2.4M raised to date. This round accelerates growth.

Investor Story


Featured Investors

Sabby Jonathan

Sabby Jonathan is a CPA and Certified in Financial Forensics who led Jonathan & Associates for 32 years. A former Mayor of Palm Desert, he brings deep finance, business and civic leadership experience—and is a repeat IZOLA investor.


"What first drew me to IZOLA was Jenny and Jeffrey’s belief that financial success and social conscience are not mutually exclusive. They have proven that conviction through disciplined execution, extraordinary hospitality and a company built with care. Their integrity has earned our confidence again and again—and is why we have invested in IZOLA several times."


Bobby Edelman · Angel Investor, San Diego

Bobby Edelman is a San Diego angel investor who has backed 170+ early-stage companies since 2019 and is a six-year member of NuFund Venture Group. At Marshall Industries, he grew the Computer Products Group from $0 to $300M and helped lead the company through its acquisition by Avnet.


"Since I first invested, I've watched Jeffrey and Jennifer turn IZOLA into one of San Diego's most beloved bakeries and a profitable, well-run business, and I believe their plan to grow beyond one location is a thoughtful one. Expansion carries real execution and investment risk, so read the Form C carefully, but I invested because of how they've met every challenge so far."

Disclosure: Bobby is an existing IZOLA investor and a personal friend of the founders. Bobby has provided this statement voluntarily, without compensation or other benefit. He has not independently audited IZOLA's financials or projections. His views are his own as of October 28, 2026, are not investment advice, and do not represent any organization he is affiliated with.

Team


Jeffrey Brown | Co-CEO - Hospitality, Growth & Story

Pulitzer Prize finalist and architect of IZOLA’s hospitality and storytelling engine. Jeffrey leads real estate, finance, capital strategy and the growth partnerships behind IZOLA’s next chapter.


Jennifer Chen | Co-CEO - Product, Systems & People

Super taster and operating architect behind IZOLA’s food, production systems and service model. Jenny leads product, people and Kaizen: every batch, process and destination must be better than the last.

Our Story


It started with 12 croissants and a basket.

When COVID hit during a trip to France, home suddenly felt very far away.

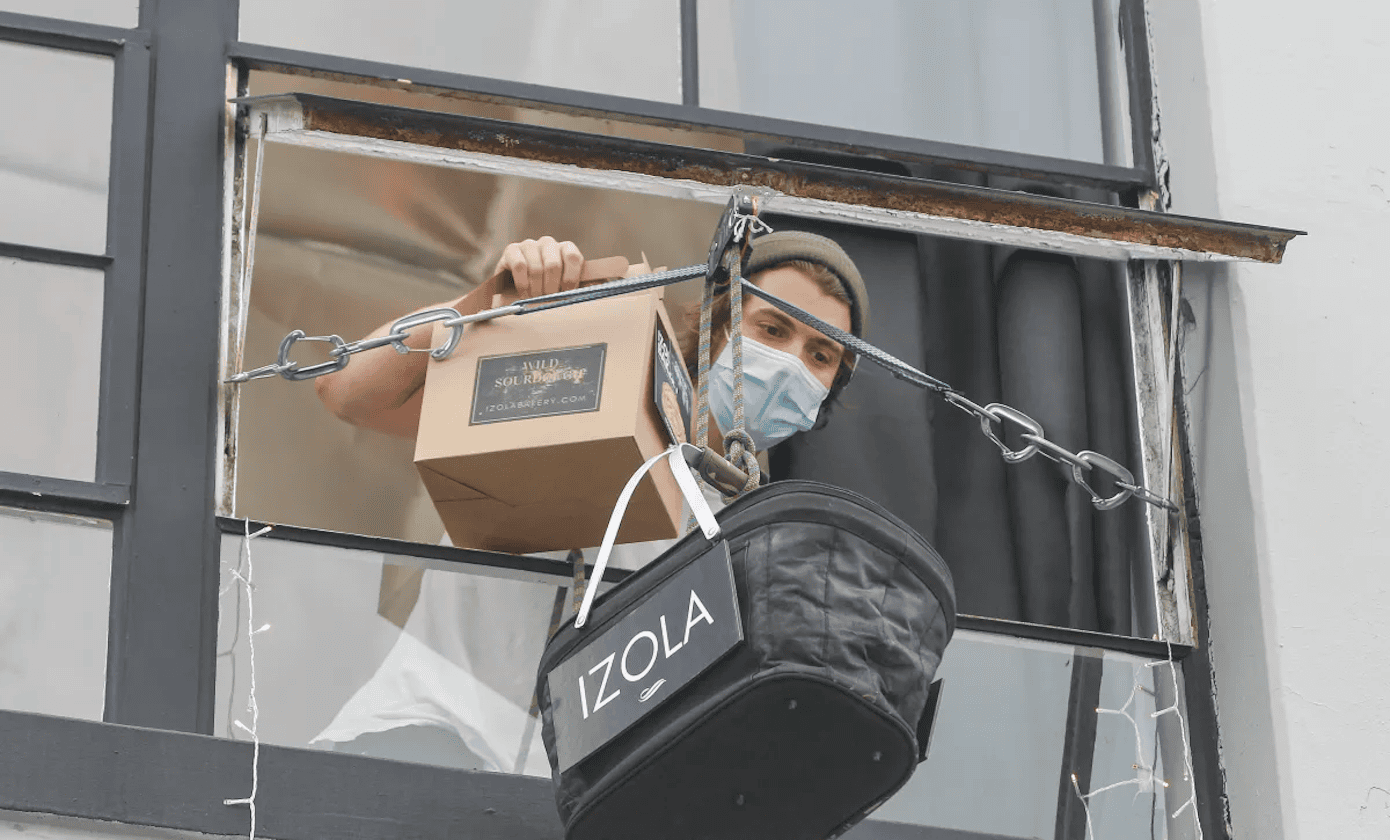
Back in San Diego, frightened and isolated, Jenny and Jeffrey began baking in the loft above their photography studio—not to build a company, but to create a little joy.

On June 10, 2020, they made 12 croissants and lowered them out the window in a basket.

Guests came back. They brought friends.

Twelve croissants became a bakery, and the bakery became a community.

What began as a small act of care grew into something larger.

The promise never changed: extraordinary food, served hot from the oven, with genuine human care.

Delivering that promise all day required reimagining how a bakery works.

The Product


Four days for a croissant worth driving for.

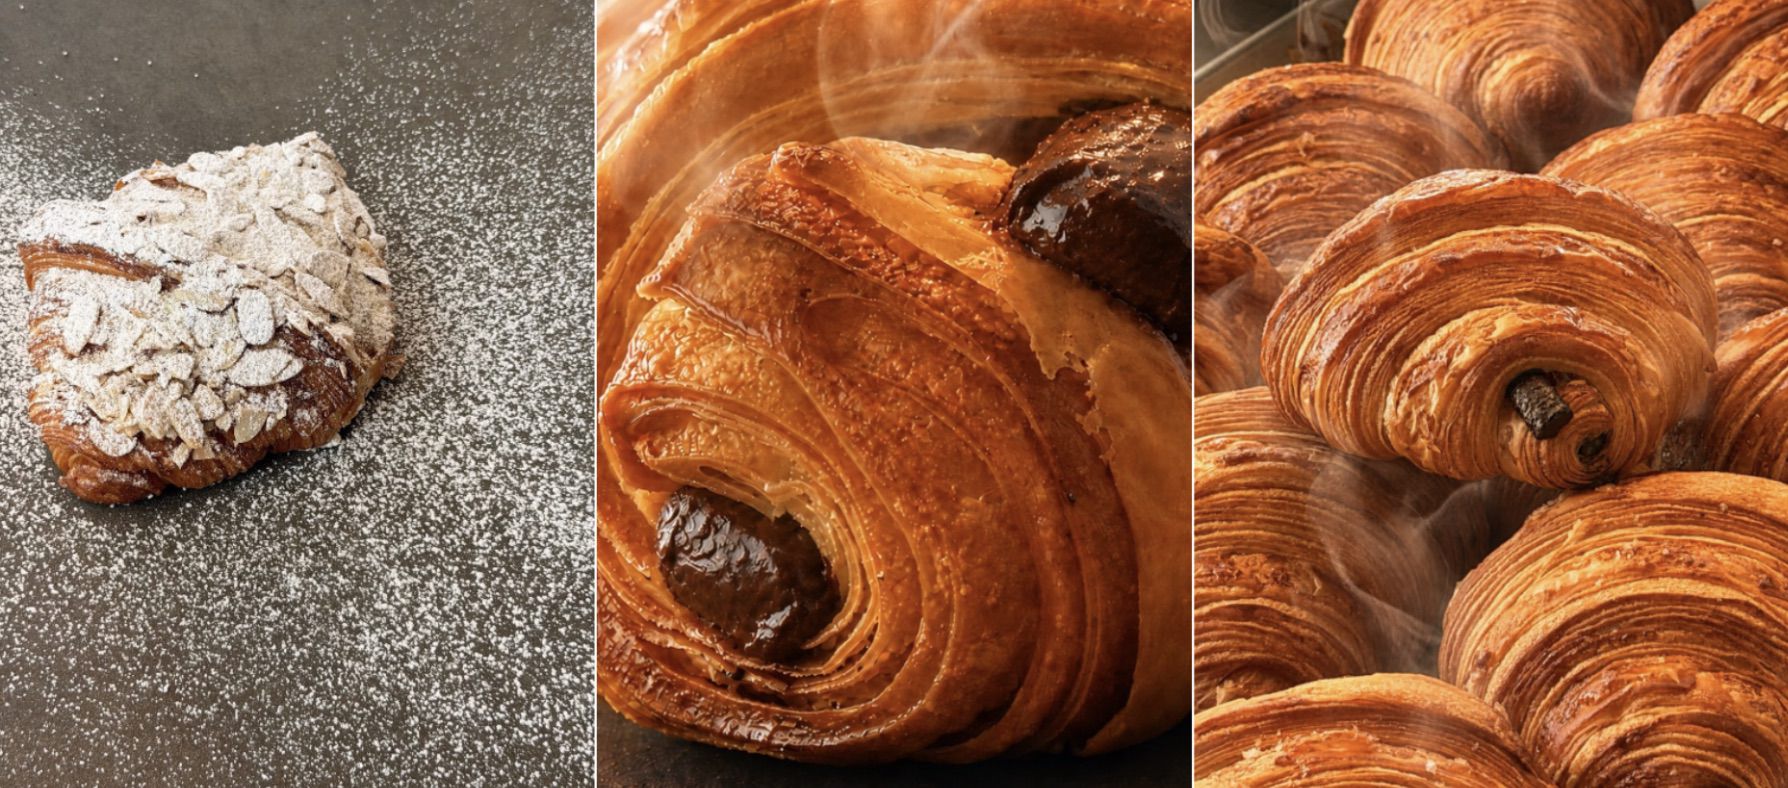
Great croissants depend on time. IZOLA’s four-day process combines careful lamination, Normandy butter and a true overnight rest to build flavor, structure and the shattering texture our guests love.

That same obsession with craft extends to our naturally leavened sourdough, made with a long fermentation for deeper flavor and character.

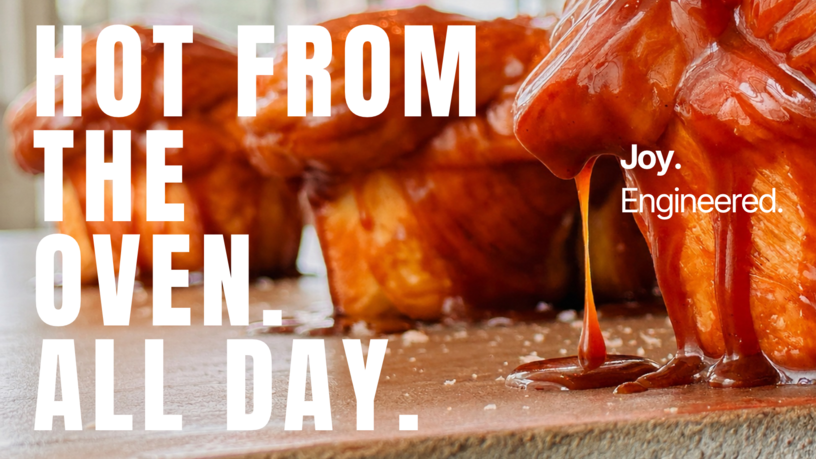
And we do something most bakeries don’t: we bake throughout the day, so guests experience our croissants and sourdough the way they were meant to be experienced—hot from the oven.

Social Proof


Named Yelp’s #1 bakery in America

Yelp named IZOLA its #1 bakery in the U.S. in 2022. Today, 1,869 guests have given IZOLA five-star Google reviews. But the numbers tell only part of the story. Guests drive hours, return again and again, bring friends—and describe an experience that goes far beyond the food.

“THE BEST! NO NOTES! This place will ruin all other croissants for you… I’ve gotten multiple other people hooked on this place also, it really does that to you.”
— Kristine C., Yelp

“Service was amazing! The staff were welcoming, friendly, and quick. They checked on us frequently and made sure if we needed anything else / if we enjoyed our food.”
— Tanya H., Yelp

“This place has it all from the amazing staff to the ridiculously delicious croissants and sourdough… This is the type of place you come for a culinary experience… they are setting another level to the game.”
— Erik A., Yelp

IzOS


Technology in service of delight.

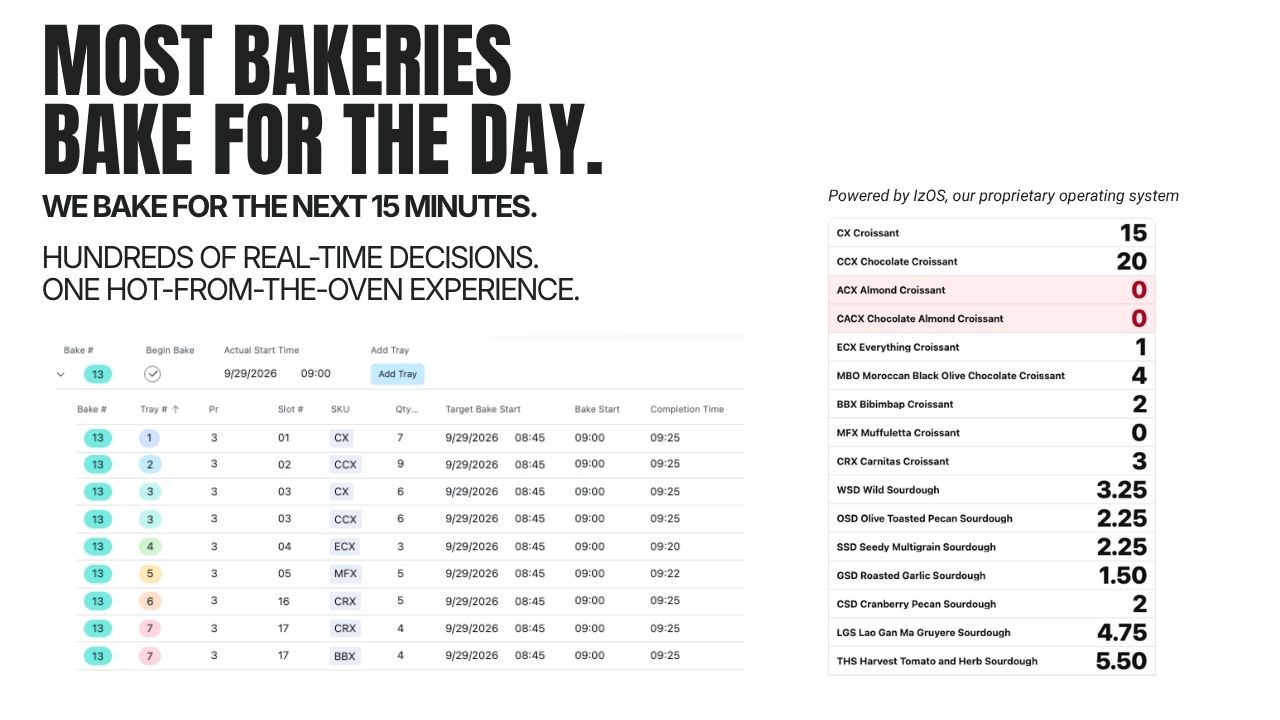
IzOS is IZOLA’s proprietary bakery operating system. Connected to our point-of-sale and online ordering systems, it updates live inventory ~50,000 times each month as guests buy in-store and online. 

IzOS turns real-time demand into serial-numbered tray-up orders for our dough team and precise bake schedules for our bakers. As trays come out of the oven, inventory updates automatically so our hospitality team knows exactly what’s available to sell. 

The platform has reduced our processing times from 40+ seconds to under 3 seconds — coordinating hundreds of behind-the-scenes decisions so we can bake for the next 15 minutes and serve croissants hot from the oven.

Hospitality


We created a new hospitality category.

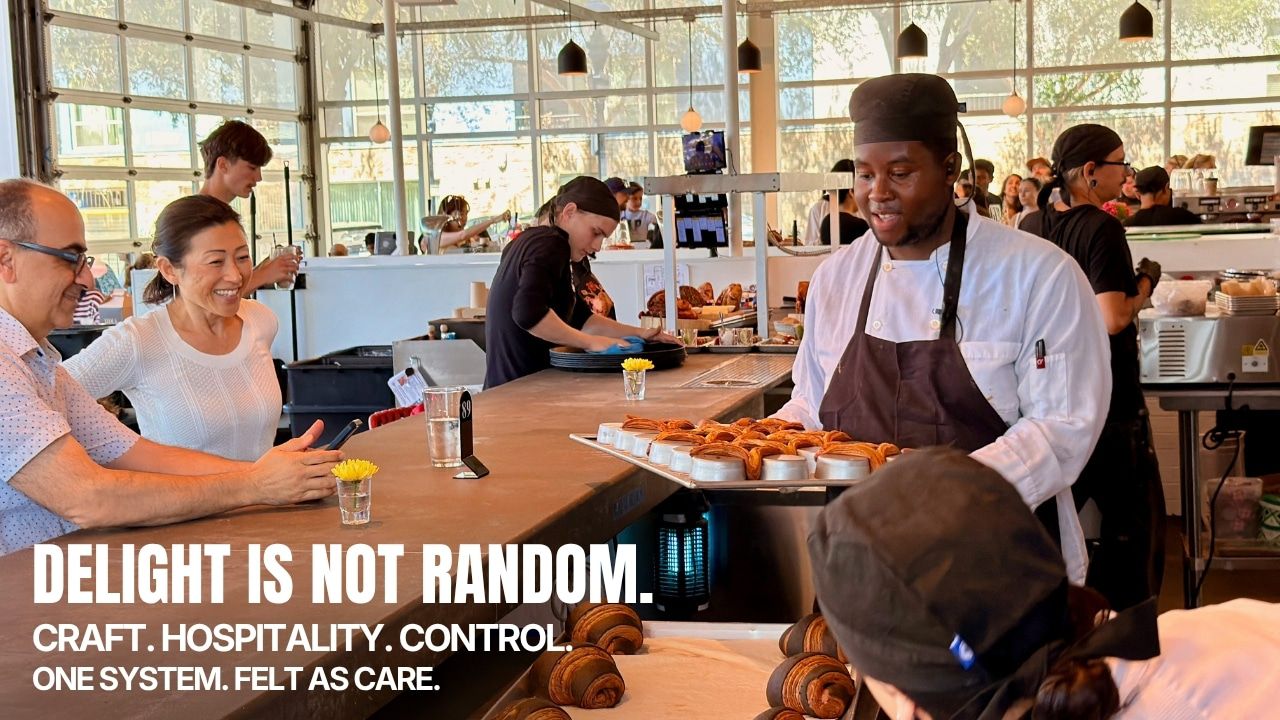
IZOLA sits between fine dining, artisan craft and quick service: handmade food and warm, high-touch hospitality delivered at high-volume speed—all served hot from the oven.

Fine dining rarely moves this fast.

Quick service rarely feels this human.


The Flagship

2025 was our first full calendar year at IZOLA's flagship location in Downtown San Diego: $3.1 million in revenue, $288K in operating income, $273K in net income, and $222K in operating cash flow—all audited. Every dollar of that revenue was generated by this single destination.

Placemaking


The flagship proved more than demand.

Guests return, bring friends and create ritual, vibrancy and community.

That devotion compounds: word of mouth brings new guests, visible demand supports pricing power, and developers see a placemaking partner—not merely a tenant.

That reputation produced a nearly turnkey second destination in a vibrant trade area, the opportunity to collaborate with a world-class ownership team, and unusually favorable occupancy economics.

Love becomes leverage.

Placemaking compounds into financial advantage.

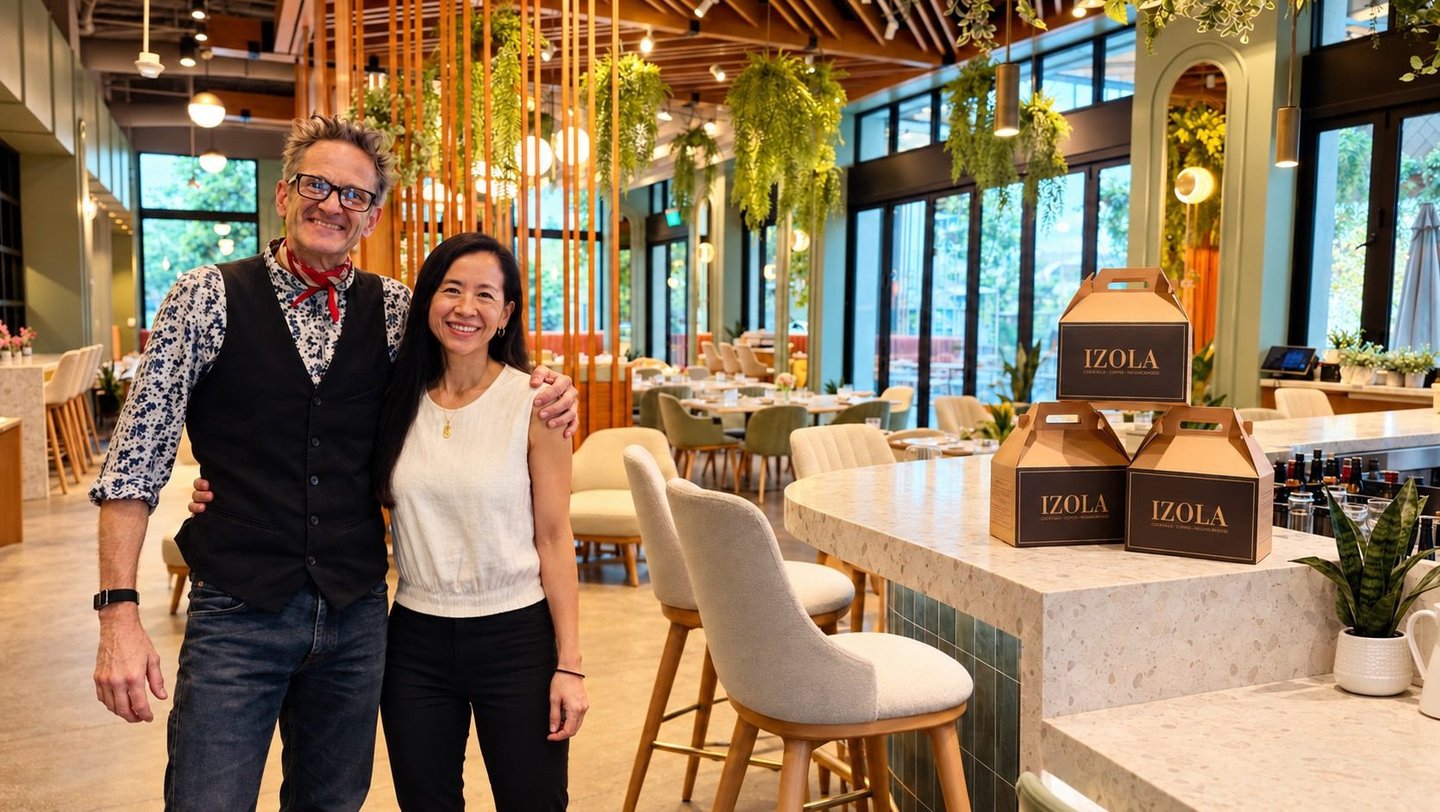
IZOLA founders Jennifer Chen and Jeffrey Brown

Scaling Craft


The question is not whether IZOLA can grow. It's whether growth makes IZOLA better.

Kaizen—continuous improvement—governs how we grow. We won’t open another destination or bring IZOLA Main online unless the quality and guest experience improve.

Traditionally, each new bakery recreates the hardest part: the complex 4 day dough production process. 

IZOLA Main centralizes that complexity in one purpose-built environment, where tighter control, repetition and shared learning can improve the dough while dramatically expanding capacity. Each destination stays focused on what guests experience: baking hot and delivering extraordinary hospitality.

Centralize the complexity. Improve the product. Protect the magic.

Izola Main


The machine wasn't the breakthrough. The process was.

Industrial lines are built for speed; artisan croissants depend on time. So we reengineered the automated process around the dough—slowing the line, splitting production into stages and restoring the critical overnight rest.

The result: dramatically more capacity, dramatically less labor—and the product gets better.

We didn’t change the croissant to fit the machine. We changed how the machine is used to protect the craft.

Platform Economics


Why IZOLA Main changes the company.

Main turns dough-making from a location-by-location constraint into shared infrastructure for growth. It centralizes specialized equipment and dough production, while each bakery focuses on baking and hospitality.

MORE PRODUCT TO SELL

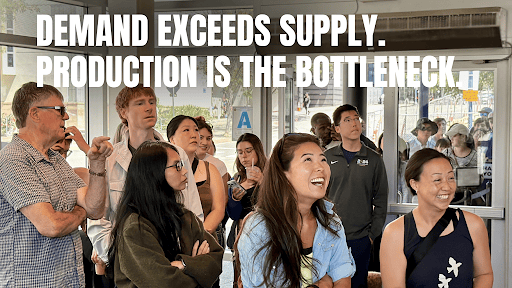
IZOLA is routinely supply-constrained, leaving thousands of dollars in demand unserved on peak days because we run out of product—not guests. Main is designed to remove that bottleneck.

STRONGER ECONOMICS

At scale, our model projects dough-production cost declining from ~11% of revenue to 2.5% and food cost from ~20% to 16.5%—strengthening economics across every destination Main serves.

Management projections are estimates. Actual results may differ.

Growth Plan


One backbone. A destination-led plan.

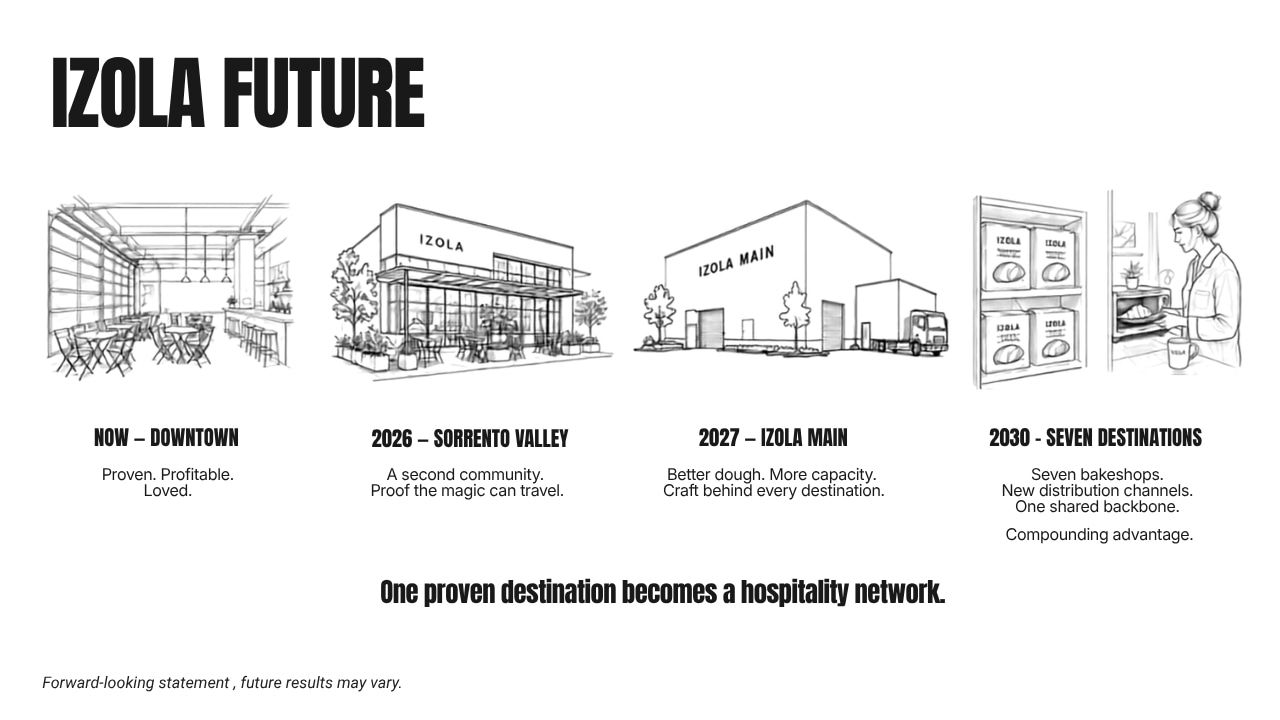
Company-owned destinations come first, with each opening gated by product quality, leadership readiness, liquidity and performance. Each adds revenue and sends more volume through IZOLA Main—increasing utilization and spreading fixed costs across a larger base.

As the destination model matures, we can add select adjacent channels: grocery and regional direct-to-consumer. Products are par-baked at IZOLA, delivered, then finish-baked and served hot from the oven—preserving the IZOLA experience.

The ambition isn’t to put IZOLA everywhere. It’s to create more experiences people love—and make each one more IZOLA than the last.

Joy + Justice


Joy for our guests. Justice in how we build.

IZOLA was founded with a dual mission: create extraordinary moments of joy and build a company rooted in justice.

Justice is practical: washable serviceware, equal tip sharing, restorative-justice hiring and leadership development from within.

The company we build matters as much as the food we serve.

Use of Funds


Capital with a clear job.

This round widens IZOLA’s margin for error.

Additional capital helps build IZOLA Main, the next destinations, build the leadership capacity for multi-unit growth, develops new distribution channels, supports IZOLA Main’s energy resilience.

The more we raise, the faster we can move from strength—without cutting corners or requiring each preceding project to fully mature before beginning the next.

The round accelerates the seven-destination plan; it does not pre-fund every future opening. Later destinations may also use operating cash flow, landlord contributions, debt or future equity.

Investor Returns


One transparent hurdle.

The current unit price reflects a forward platform valuation. Investors are underwriting whether Sorrento Valley and IZOLA Main can turn one proven destination into the modeled seven-destination platform.

We model a 2× planning target—not 5×—five-year case. Under full-raise assumptions, 2× requires ~$87.1M of enterprise value. At 9× EBITDA, that requires ~$9.7M of EBITDA; our 2030 plan models ~$9.3M. At 8×, the plan models ~1.71× gross value; at 9×, ~1.92×.

These figures assume 15% future dilution, 3% exit costs and $500,000 net debt, before investor fees and taxes.

At a full raise, Jenny and Jeffrey retain ~76.7% combined ownership. Returns depend on execution and an actual liquidity event—not a quick flip.

No return or liquidity event is guaranteed. A total loss could occur.

What's Next


The experience is proven. The next chapter is underway.

IZOLA began with 12 croissants and a basket.

Today, IZOLA proves that extraordinary food, served hot from the oven with genuine human care, can become a powerful business.

Now we are building the operating system to bring that experience to more communities.

The product will improve.

The scale will change.

The promise will not.

Invest in IZOLA—and own a piece of the hospitality category we are building.

Financial Model


Test the investment, not just the highlights.

Audited history governs. The read-only IZOLA Investor Decision Tool separates audited results from management assumptions and presents the operating plan, downside case, raise levels, ownership, dilution and performance required for the modeled return.

OPEN THE LIVE INVESTOR DECISION TOOL →

Start with the first tab. Deeper supporting schedules follow.

Management projections, operating assumptions and illustrative returns are estimates, not guarantees.

$

Deal terms Special


Minimum investment
$1,000
The smallest investment amount the issuer is accepting in this offering.
Security Type
Membership Units
Price Per Unit
$2.10 - $2.30

The price per Unit (the “Purchase Price”) is $2.10 for the first $250,000 of accepted subscriptions, $2.20 for accepted subscriptions above $250,000 through $500,000, and $2.30 thereafter through the Maximum Offering Amount.


Minimum Offering Amount
$75,000
Maximum Offering Amount
$5,000,000
Deadline
October 31, 2027
IZOLA campaign will end on .
Learn more
Logo of IZOLA
IZOLA
People drive hours for IZOLA. One profitable destination. Now building what comes next.
Raised amount
0 — $249,999.99
$250,000 — $250,000
$250,000.01 — $499,999.99
$500,000 — $5,000,000
Close
How it works

Documents

Republic (OpenDeal Portal LLC, CRD #283874) is hosting this Reg CF securities offering by Tallgrass Pictures LLC. View the official SEC filing and all updates:
Official SEC Logo Form C SEC.gov
Company documents
Subscription Agreement IZOLA_Form C.pdf

About IZOLA

Legal Name
Tallgrass Pictures LLC
Founded
Nov 2004
Form
California LLC
Employees
47
Website
izolabakery.com
Social Media
Headquarters
Google Map location of of IZOLA
1429 Island Avenue , San Diego, CA
Headquarters
1429 Island Avenue, San Diego, CA, United States 92101

IZOLA Team
Everyone helping build IZOLA, not limited to employees

Profile picture of Jeffrey Brown
Jeffrey Brown
Co-CEO
Pulitzer Prize finalist and architect of IZOLA’s hospitality and storytelling engine. Jeffrey leads real estate, finance, capital strategy and the growth partnerships behind IZOLA’s next chapter.
Profile picture of Jennifer Chen
Jennifer Chen
Co-CEO
Super taster and operating architect behind IZOLA's food, production systems and service model. Jenny leads product, people and Kaizen: every batch, process and destination must be better than the last.
Jeffrey Brown
Co-CEO
Jennifer Chen
Co-CEO

Press

Award-winning East Village bakery Izola serves up fresh b...
ABC 10 News San Diego KGTV ABC 10 News San Diego KGTV
·
May 13, 2025

The bakery partners with organizations that help people who were formerly incarcerated, recovering from addiction, or exp...

Izola Bakery Is On a Mission to Build A Cathedral of Brea...
San Diego Magazine San Diego Magazine
·
Mar 4, 2023

How a pair of hobbyists turned a pandemic side hustle into a croissant empire

Yelp's top US bakery is in a downtown San Diego loft
FOX 5 San Diego & KUSI News FOX 5 San Diego & KUSI News
·
Oct 6, 2022

A little bakery in a historic East Village loft was named best in the U.S. by Yelp.

San Diego bakery's warm bread is coming right down, by ba...
Los Angeles Times Los Angeles Times
·
Dec 24, 2020

COVID-safe deliveries from third-floor window are drawing crowds to 6-month-old Izola Bakery.

FAQ

What are the risks associated with investing in equity securities?

What are the risks associated with investing in equity securities?

Equity security investments are subject to market fluctuations, company-specific risks, and general economic conditions. Prices can be volatile, and there is risk of losing the invested capital. 


Remember, investing always carries risks, and it's essential to conduct thorough research or consult with a financial advisor before making investment decisions.

How do I earn a return?

How do I earn a return?

We are issuing equity in our company. You may realize returns if the company “exits,” meaning it is acquired or goes public at a higher price than you paid for it, or if you sell the securities at a higher price than you purchased them for. There is also a risk that you could lose your entire investment if the company fails. Startup investing is risky, so there’s no guarantee of a return on this kind of investment. It’s always best to refer to the individual offering documents provided by the company to understand your investment risks.
Where can I review the supporting financial materials?

Where can I review the supporting financial materials?

OPEN THE IZOLA INVESTOR DECISION TOOL→

OPEN THE IZOLA FINANCIAL PACKET →

OPEN IZOLA CAMPAIGN CLAIMS & METHODOLOGY →

The read-only Investor Decision Tool contains the operating plan, audited-results reconciliation, Sorrento Valley and IZOLA Main economics, raise tiers, use of proceeds, ownership analysis, downside case and investor-return sensitivities.

The IZOLA Financial Packet includes the signed audited financial statements and supporting diligence materials.

The Claims & Methodology file documents the calculations, sources and qualifications behind the principal campaign claims.

Historical results are audited or derived directly from audited figures where stated.

Management projections, proposed transaction terms and future operating assumptions are unaudited estimates and are not guarantees.

What reporting will investors receive?

What reporting will investors receive?

IZOLA intends to provide quarterly investor updates covering:

  • Revenue and material operating trends;

  • Location #2 progress and performance;

  • IZOLA Main construction, commissioning and operating milestones;

  • Progress against the company’s operating plan; and

  • Material changes, delays, risks or decisions affecting the business.

IZOLA will also provide annual unaudited financial statements and required Regulation Crowdfunding reports in accordance with applicable law.

Our investor community deserves to understand what is working, what is not and what we are learning. We intend to communicate candidly—not only when the news is easy.

What are the principal risks?

What are the principal risks?

The principal risk is execution.

Sorrento Valley or IZOLA Main may cost more, open later or perform below expectations. Future destinations may ramp more slowly than planned. Financing or refinancing may be delayed, reduced or repriced.

Expansion may place pressure on management, culture, staffing, systems, product quality, hospitality, liquidity and working capital.

Future financing may dilute investors, and there is no guaranteed distribution, redemption, secondary market or liquidity event.

Investors could lose some or all of their investment and should review the complete risk disclosures in the Form C before investing.

Have prior Regulation Crowdfunding reporting gaps been addressed?

Have prior Regulation Crowdfunding reporting gaps been addressed?

Yes. IZOLA's EDGAR Portal contains IZOLA annual reports covering fiscal years 2022 through 2025.

The June 24, 2024 Form C-AR includes audited financial statements for 2023 and 2022. The April 30, 2026 Form C-AR includes audited financial statements for 2025 and 2024.

The 2026 filing disclosed that it was filed to remedy prior reporting gaps. The required historical reports are now on file.

IZOLA intends to remain current with all ongoing Regulation Crowdfunding reporting requirements.

Who owns IZOLA Main?

Who owns IZOLA Main?

The IZOLA Main property is owned by 3320 Fairmount, LLC, a founder-owned entity. Investors in Tallgrass Pictures, LLC do not own the real estate.

Tallgrass Pictures, LLC dba IZOLA is expected to receive the operating benefit of the purpose-built facility through its occupancy and operating arrangements.

The tenant improvement is planned to be financed jointly from the core Regulation Crowdfunding use-of-proceeds plan and debt sources, subject to lender closing and funding conditions.

The signed 2025 audit also discloses that Tallgrass Pictures, LLC dba IZOLA guarantees repayment of certain obligations of 3320 Fairmount, LLC.

At December 31, 2025, the guaranteed Live Oak principal balance, which is for the IZOLA Main land, was approximately $1.11 million. The audit states maximum potential future principal exposure of $2.05 million, plus unpaid interest. Tallgrass Pictures, LLC dba IZOLA receives no guarantee fee.

The audit also reports a $211,209 note receivable by Tallgrass Pictures, LLC dba IZOLA, from 3320 Fairmount, LLC, bearing 7% interest and amortizing over 25 years.

The contemplated tenant improvement loans have seven-year terms and 25-year amortization schedules, creating a substantial balloon-payment or refinancing requirement at maturity.

The final refinancing, guarantee, rent and occupancy structures may change.

The complete property capital stack, debt schedule and operating assumptions are available in the IZOLA Investor Decision Tool. Final loan documents and occupancy arrangements control.

What exactly am I buying and how could it create value?

What exactly am I buying and how could it create value?

Investors purchase Class B non voting units  in Tallgrass Pictures, LLC, which does business as IZOLA.

Investors will not have day-to-day management control.

Potential investor value could come through future distributions, a company or third-party tender offer, a recapitalization, a sale or another liquidity event.

None is guaranteed.

This is permanent, long-term equity. It is not redeemable at the investor’s request, is expected to be illiquid and could result in the loss of some or all of the investment.

Investors should review the Form C, subscription agreement and Tallgrass operating agreement before investing.

Still have questions? Check the discussion section.
Show all FAQ

Risks

Operating history is limited, and recent profitability may not persist.
The Issuer reported a $594,541 net loss in 2024 and $272,687 of net income in 2025. A full year at Island Avenue materially affected the comparison. Its history provides a limited basis for evaluating new locations and production methods. Expansion spending, cost increases or weaker demand could return the Issuer to losses and negative cash flow.
Economic conditions, public-health disruptions and competition may reduce demand.
IZOLA depends on discretionary customer spending on a limited range of bakery and café products. Inflation, economic weakness, changing preferences, public-health restrictions and other disruptions may reduce traffic, increase costs, interrupt supplies or impair financing while rent, debt service and payroll remain due. Local bakeries, restaurants, grocery stores and national brands compete on convenience, price, product, marketing, locations and talent.
The $75,000 target is far below the identified capital need.
Management presently identifies approximately $425,000– $825,000 of combined Main and Second Site need before additional contingency and working capital. A target close does not fund the full plan, and the Issuer may need more equity, debt or operating cash flow promptly.
The Issuer may need additional financing on unfavorable terms.
There is no assurance the Issuer will raise $500,000– $1,000,000, draw its approved loan or obtain other capital when needed. Future financing may be costly, secured, restrictive, senior to the Units or highly dilutive.
Working capital and construction demands may strain liquidity.
At December 31, 2025, current liabilities exceeded current assets by $90,893. The Issuer used $536,464 in investing activities during 2025 and depends on cash flow and financing to fund concurrent expansion projects.
Main’s financing, completion and projected efficiencies are uncertain.
Completion depends on financing, satisfactory appraisals and lender requirements, construction costs, permits and timely access to funds. A financing commitment does not assure proceeds will be available when needed. Additional equity, operating cash flow or financing may be required. Construction, landlord, utility, vendor, installation, software and training problems could delay, reduce or prevent completion and increase costs before Main generates benefits. Projected capacity, labor and food-cost improvements are process models, not guarantees. See Sections 4 and 8.
The Second Site may be delayed, over budget or unsuccessful.
The BioVista lease was executed September 18, 2026 and creates rent and other contractual obligations even if the location opens late or underperforms. It will require equipment, permits, staffing, inventory and working capital; it may never open, cost more than $225,000, ramp slowly or cannibalize Island Avenue rather than double revenue. Termination rights are limited to the lease’s terms.
Two simultaneous expansion projects increase execution risk.
If the Second Site proceeds, management must develop it while completing Main and operating Island Avenue. Management attention, cash, systems or staffing may be insufficient, harming existing operations and both projects.
The business is concentrated in San Diego and a limited number of locations.
Substantially all 2025 revenue came from Island Avenue, and current expansion remains concentrated in San Diego. Local economic conditions, customer traffic, construction, access restrictions, earthquakes, fires or other disruptions could disproportionately affect results. Additional locations may underperform or shift sales from existing locations instead of generating the anticipated growth
Founder succession and contractual repurchase rights may affect ownership and control.
The Operating Agreement’s transfer and repurchase provisions and the founders’ Side Agreement can change ownership or control without providing liquidity to other investors. Certain repurchases use a Manager-determined value and may be paid in installments under the applicable agreement. The founders’ Side Agreement has its own purchase rights and valuation process. See Subscription Agreement Exhibit 1.
C-corporation tax treatment can result in two levels of tax.
Although a limited liability company, the Issuer has elected C- corporation tax treatment. Income can be taxed at the entity level and distributions treated as dividends can be taxed again to investors. Company losses generally do not pass through to investors. These consequences may reduce after-tax returns. See Section 10.
Binding arbitration may limit procedural rights.
The Operating Agreement generally requires JAMS arbitration in San Diego, with stated exceptions. Arbitration may be costly, may limit discovery and appeal, and may prevent a Member from pursuing claims in court to the extent enforceable. Federal securities-law rights cannot be waived.
Specialized equipment, supplies and centralized production create operational dependencies.
Ingredients, packaging, bakery and refrigeration equipment, spare parts, utilities, contractors and technical support may be unavailable or more expensive. Imported equipment and parts may face tariffs, shipping delays, certification requirements, installation difficulties and limited service availability. Centralizing production at Main also concentrates risk: equipment failure, power loss, contamination or a production interruption could affect multiple locations. The Issuer may be unable to pass cost increases to customers, and backup arrangements and insurance may not cover all losses.
Intellectual property protection may be inadequate.
Trademarks, recipes, processes, designs, domains and confidential know-how may be challenged, copied or lost. Enforcement can be expensive, and the Issuer may be accused of infringing third-party rights.
The Issuer depends on Jeffrey Brown and other key personnel.
Jeffrey is founder, principal owner and sole Manager. Jennifer and a limited leadership group also hold important operating knowledge. Death, disability, departure, distraction, conflict or inability to recruit capable managers could materially harm the Issuer. Key-person insurance may be unavailable or insufficient.
Damage to IZOLA’s reputation or inconsistent quality may reduce sales.
Customer trust depends on product consistency, service and hospitality. Negative publicity, reviews or social-media allegations about food safety, employment or other matters can spread quickly and reduce demand even when unsubstantiated. Centralized production, additional locations, wholesale or shipping may reduce freshness, introduce logistics failures or make the customer experience less distinctive.
Technology, cybersecurity and privacy failures could disrupt operations.
Online ordering, payment, point-of-sale, accounting, scheduling and customer-data systems depend on third parties. Outages, fraud, ransomware, data breaches or vendor failure could interrupt sales, compromise personal information, create liability and damage trust. Privacy and data- security requirements may change or require costly compliance measures. The Issuer’s safeguards and insurance may not prevent or fully cover a loss.
The Issuer does not provide the internal-control assurances required of certain public companies.
The Issuer is not an Exchange Act reporting company and is not currently required to provide the management assessment and auditor attestation of internal control over financial reporting applicable to certain public companies under Section 404 of the Sarbanes-Oxley Act. Its controls may not prevent or promptly detect errors, fraud or reporting deficiencies. Growth may require improvements that consume management time and increase expenses.
Food safety and allergens could cause serious harm.
Foodborne illness, contamination, mislabeled allergens, foreign material, sanitation failures or supplier problems could injure customers, require a recall or closure, create liability and damage the IZOLA brand. Insurance may not cover all losses.
The business is regulated and has experienced permitting disruption.
Bakery, restaurant, construction, alcohol, health, fire, employment, accessibility and environmental rules apply. The prior operation experienced a permitting-related closure. Changes in law, violations, inspections or permit delays could increase costs or interrupt operations and expansion. Insurance may exclude some risks, have inadequate limits or be unavailable at a reasonable cost.
Labor availability and employment claims may increase costs.
The Issuer needs bakers, production, front-of-house and managers in a competitive labor market. Wage increases, turnover, training failures, scheduling, classification, meal-and- rest-break, harassment, discrimination, union, immigration or workplace-injury matters could raise costs or liability
The Operating Agreement permits purposes that may not maximize profit.
In addition to operating IZOLA bread cafés and related marketing, licensing, and sales activities, Section 1.2 authorizes the Issuer to promote social and environmental change through positive business practices selected by the Manager, and states that this additional purpose may not be operated for profit. The Manager may therefore consider objectives other than maximizing short-term profit or distributions.
Affiliate transactions create conflicts of interest.
Section 5.1 generally requires affiliate terms that, in the aggregate, are substantially no less favorable to the Issuer than terms obtainable from unaffiliated persons. Subscription Agreement Section 4.2(a)(i) includes an acknowledgement that the investor has reviewed all of the disclosed affiliate transactions identified in the Subscription Agreement, they have had the opportunity to ask questions, examine the available underlying documents, and consult independent advisers regarding the affiliate transactions, and they have provided fully informed consent to the affiliate transactions. The investor acknowledges and agrees that any future affiliated transaction may create actual and potential conflicts of interest because the Manager may negotiate, approve, administer, amend, or enforce arrangements in which the Manager or another affiliate has a financial interest, and each investor has affirmed, acknowledged and agreed that the Issuer, in the course of its business activities, may enter into an affiliate transaction provided all such contracts and agreements with affiliates contain provisions and conditions which in the aggregate are substantially no less favorable to the Issuer than the provisions and conditions which could be obtained from persons which are not affiliates of Members or the Manager. This may limit an investor’s ability to challenge the disclosed economics, as well as the disclosed conflict. The consent is subject to the governing-document, informed-consent and nonwaivable-law limits in Section 13 of the Subscription Agreement. Sections 3.4 and 5.1 remain controlling, and statutory fiduciary duties and required transaction-specific disclosures and approvals are preserved. The Manager or founders may be on both sides and receive different benefits. See Section 1.7.
Affiliate ownership and personal guarantees create conflicts concerning Main.
Jeffrey Brown and Jennifer Chen own 3320 Fairmount LLC and have personal guarantee exposure in the disclosed financing arrangements. Their interests as property owners and guarantors may differ from those of Tallgrass investors. Rent, improvements, debt, refinancing, enforcement and expense allocation may benefit the affiliate or reduce personal exposure while reducing Company cash. Tallgrass does not own the real estate and has advanced funds to the affiliate. To the extent required, Issuer has obtained written consent for this offering. See Section 9 and Exhibit G for the arrangements and lease terms.
An investor may lose the entire investment.
The Units are speculative securities of a privately held expansion-stage food and hospitality company. The Issuer may fail, become insolvent, restructure or sell assets for less than the amount needed to satisfy creditors and return capital to Members.
Affiliate debt and property defaults could expose Issuer assets and disrupt Main.
The 2025 audit describes Tallgrass’s guarantee of a Live Oak loan to 3320 Fairmount LLC, with $1,109,930 outstanding at December 31, 2025 and maximum potential future guaranteed principal of $2,050,000 plus interest. For that Live Oak loan, Tallgrass is the guarantor rather than the borrower. Default could require payments, divert cash or cause loss of assets. A property or financing default could also lead to foreclosure or loss of Main, subject to the operative documents and legal protections, resulting in lost improvements, relocation costs and business interruption. The planned Self-Help loans would instead make Tallgrass and 3320 Fairmount co-borrowers for up to $3,777,260, secured by property, equipment and other assets, with both founders’ full personal guarantees. The financing remains subject to closing conditions. See Section 9.
Existing debt may restrict operations and reduce proceeds available in a sale.
Debt service consumes cash. The 2025 audit describes covenants restricting additional indebtedness, capital expenditures, distributions, liens, asset sales and mergers, and reports compliance as of December 31, 2025. Future noncompliance could impair financing and liquidity. If a future transaction constitutes a Change of Control under the outstanding revenue-sharing-note agreement, the agreement provides for a payment equal to the Maximum Payment Amount less aggregate prior payments. That obligation may reduce equity sale proceeds or affect transaction structure and economics. See Section 7.3.
Compensation and other payments to management may reduce funds available for expansion or distributions.
Compensation and bonuses described in Section 6.1, reimbursements and other permitted arrangements use Company resources. The Manager participates in these decisions and may have interests different from those of investors. Investors cannot require the Company to apply those funds instead to expansion, debt repayment or distributions. See Section 9 and Subscription Agreement Exhibit 2.
Forecasts and non-GAAP measures are uncertain.
Revenue, EBITDA, capacity, labor savings and food-cost forecasts depend on assumptions that may not occur. EBITDA omits important costs and should not be treated as cash available to investors. Actual results may be materially worse.
Prior offerings and ongoing securities compliance may expose the Issuer to claims, costs or fundraising restrictions.
The Issuer has conducted prior securities offerings and has historical annual-reporting delinquencies described in Section 8.6. A finding that an offering, disclosure or practice failed to comply with applicable law could, depending on the violation, result in enforcement, penalties, investor claims or restrictions. Later filings do not by themselves resolve every earlier claim. Incomplete disclosures, untimely amendments or reports, bad-actor issues or failure to obtain required reconfirmations may delay sales, require refunds of open commitments or restrict future fundraising. Defense costs and payments would reduce resources available for operations.
SEC filing does not constitute approval of the investment.
Neither the SEC nor any state securities authority has approved the Securities, passed on the merits of this investment or endorsed the adequacy or accuracy of these disclosures. Availability on EDGAR does not assure investment quality or compliance with law.
The Securities are offered under an exemption from registration.
The Offering and Units are not registered under the Securities Act and rely on Section 4(a)(6) and Regulation Crowdfunding. The required information differs from that provided in a registered public offering. Investors could make a different decision if additional information were available.
The Manager has broad discretion over the use of proceeds.
Section 5 contains estimates. Subject to the Operating Agreement, applicable law, binding obligations and disclosure requirements, the Manager may change the amount, timing or priority of expenditures. Actual uses may differ materially, investors may disagree with the choices, and expenditures may not produce anticipated results.
Offering expenses reduce available cash, and compensation Units dilute other holders.
Cash fees and expenses described in Sections 2 and 5 reduce proceeds available to the Issuer. Total expenses depend on the amount raised, the negotiated marginal fee schedule, payment methods and other expenses. Securities issued as intermediary compensation dilute other holders.
The Issuer may reject subscriptions or waive the minimum subscription amount.
Subject to the Offering terms and applicable law, the Manager may accept or reject a subscription, in whole or in part, or waive the minimum in writing for a particular subscription. Investors may receive different investment allocations or be unable to acquire the intended number of Units. The Offering may attract fewer investors or less capital than anticipated. See Section 1 and the Subscription Agreement.
The Offering may be extended or ended before its stated deadline.
Subject to Section 1.9 and applicable law, the Issuer may extend the Offering or end it early. An extension may delay completion of an unclosed investment; an early end may limit funds raised or the opportunity to invest. Applicable cancellation, notice and reconfirmation requirements remain as described in the Offering documents.
The intermediary does not endorse the investment.
Republic’s role as funding portal and any diligence, posting or transaction services do not constitute a recommendation, guarantee of disclosure accuracy or assurance that investors will receive a return.
Control is highly concentrated and investors have almost no management power.
The Operating Agreement gives the Manager exclusive control. Except for narrow contractual or nonwaivable rights, Members have no right to participate in management, bind the Issuer, approve ordinary decisions or call meetings. Investors cannot direct the use of proceeds or require the Issuer to follow their preferred strategy.
Jeffrey Brown is extraordinarily difficult to remove as Manager.
Section 3.6 generally prevents Jeffrey’s removal unless a majority of voting Units excluding his Units obtains a court judgment establishing fraud in the performance of his Manager duties. Poor performance, disagreement, negligence short of the contractual standard or an unpopular strategy may not permit removal.
Unknown risks may be material.
The Issuer cannot identify every risk. Changes in law, tax, insurance, weather, disaster, public health, supply chain, financing markets or other circumstances could materially affect the Issuer and the Units.
Investors grant the Manager the proxy and power-of-attorney rights set forth in the Operating Agreement and Subscription Agreement.
Those provisions are intended, to the fullest extent enforceable, to permit the Manager to take actions and execute documents authorized by the governing documents in connection with financings, issuances, recapitalizations, amendments, conversions, mergers, acquisitions, sales, drag-along transactions, admissions or substitutions of Members, dissolution and other approved Issuer actions. Investors may have limited or no ability to withhold a separate signature or consent where the governing documents authorize the Manager to act on their behalf.
There is no public market and transfers are restricted.
No trading market exists or is expected. Federal law generally restricts transfers for one year, and the Operating Agreement imposes additional rights of first refusal, consent, securities-law and adverse-effect restrictions. Investors should be prepared to hold indefinitely. The Subscription Agreement also restricts transfers during the Offering and for twelve months after the final Closing to the categories described in Rule 501(a), unless the Manager consents in writing to another lawful transfer. That contractual period can extend beyond the statutory restriction measured from the issuance of a particular investor’s Units.
Information available to investors will be more limited than for a public reporting company.
Regulation Crowdfunding annual reporting is less extensive than Exchange Act reporting. The Issuer may lawfully terminate annual reporting when the applicable conditions are met. Separate rights under the Operating Agreement and nonwaivable law remain applicable; the Subscription Agreement does not promise additional periodic reporting rights. Reduced information may make it harder to assess the investment or find a buyer.
Units have no maturity date, promised repayment or required distributions.
The Manager determines available cash after reserves, liabilities and reinvestment and may retain all cash indefinitely. Investors cannot demand repayment or redemption because of poor performance or a need for liquidity. Upon liquidation, creditors and any holders with senior rights are paid before residual amounts are available to investors. Investors may recover nothing.
The Manager may issue additional Units and create senior classes.
The Operating Agreement permits additional capital raises, admission of new Members and creation of classes with liquidation, voting or other rights superior to existing Units, subject to its terms and applicable law. Jeffrey is Manager and presently holds a majority of the working-record Units, so investors may be diluted or subordinated without their individual approval where permitted by the Operating Agreement and law. The Subscription Agreement obtains advance contractual consent and implementing-amendment authority for future issuances and their class rights, subject to the Operating Agreement, required approvals and nonwaivable law; it does not itself amend the Operating Agreement.
Investors may be bound without a new signature.
Pursuant to the proxy and power of attorney, the Manager may not need to obtain advance consent for certain transactions. To the extent consistent with the Operating Agreement and applicable law, the proxy and power of attorney may bind an investor. Section 13.3 protects against an otherwise unauthorized enlargement of a Member’s obligations. Separately required approvals, actual-transaction disclosures and nonwaivable rights remain applicable.
An investment crossing a pricing threshold may purchase Units at more than one price.
The first $250,000 is offered at $2.10 per Unit, the next $250,000 at $2.20 and subsequent Units at $2.30, as described in Section 1.3. An investment crossing a threshold is divided between the applicable prices, so equal investment amounts can purchase different numbers of Units. No public market or independent appraisal establishes these prices. A higher tier does not demonstrate increased value, an early-bird price does not assure appreciation, and future financings may occur at lower prices. See Section 1.4.
The Manager has broad exculpation and may pursue outside opportunities.
The Operating Agreement limits the Manager’s liability except for fraud, intentional misconduct or intentional violation of law and permits the Manager, Members and affiliates to pursue outside or even competitive ventures without presenting opportunities to the Issuer. These provisions are subject to nonwaivable limits under applicable law, may limit investor remedies, and permit conflicts.
Company-funded indemnification may reduce the value available to investors.
The Operating Agreement limits liability and provides indemnification for covered persons subject to its terms and applicable law. Company assets, including invested capital, may pay covered claims and expenses, leaving less for operations or distributions. These provisions may also limit investor remedies. See Section 6 and Subscription Agreement Exhibit 1.
Investors may be required to participate in an Approved Transaction.
The Operating Agreement’s Section 8.6 permits a majority of outstanding Units to compel a sale of all Units to an independent third party with specified allocation and liability rules. An investor may have to sell or exchange Units at a time or price the investor dislikes, receive illiquid or contingent consideration, and bear proportionate escrows, expenses, adjustments, and seller indemnities. Other holders may receive separate lawful service or rollover benefits. The investor may be represented without a fresh signature and bound by the representative’s authorized post-closing settlements. These powers can materially reduce individual negotiating leverage and control over timing and liquidity.
A conversion or reorganization can change the form of the investment.
Section 13.16 provides contractual authority to produce a corporate form while preserving relative ownership, voting, and economic positions. Statutory class approvals and other mandatory requirements remain applicable. The Subscription Agreement supplies cooperation and legally delegable proxy authority for actual approved transactions and successor documents, which may reduce the need for fresh investor signatures. The resulting securities, administration, tax consequences, and rights may differ from those of the Units.
Public-market lockups may continue to restrict sales.
A listing or public offering does not promise liquidity for investors. Section 7 of the Subscription Agreement permits lockups in initial and subsequent covered transactions, including periods when the investor is not selling. Other holders may receive releases that are not extended to the investor. Registration, inclusion as a selling holder, and a public market for the investor’s particular securities are not assured.
Dissociation can eliminate governance and information rights.
After a dissociation event, a Member generally becomes only an economic-interest owner, loses voting, management and most information rights, and receives no cash or assets merely because of dissociation. Issuer or assignee purchase rights may then apply.
Show all Risks

Discussion

Ask questions and share feedback with the IZOLA team below. If you have support related questions for Republic, please contact investors@republic.co.
Loading
Logo of IZOLA

IZOLA

Invest in IZOLA
Republic

Giving everyone access to early-stage startup investing

For investors
  • Why invest
  • How it works
  • FAQ
  • Risks
  • Privacy policy
  • Accessibility
  • Cookie Preferences
  • Form CRS
For startups
  • Why raise
  • Learn
  • FAQ
  • Tokenized assets
Company
  • About
  • Insights
  • Events
  • Contact
  • Security
  • We're hiring!
Dollar Refer a startup, get $2,500

Invest in the app

Android app iOS app

Invest in the app

Android app iOS app

This site (the "Site") is owned and maintained by OpenDeal Inc., which is not a registered broker-dealer. OpenDeal Inc. does not give investment advice, endorsement, analysis or recommendations with respect to any securities. All securities listed here are being offered by, and all information included on this Site is the responsibility of, the applicable issuer of such securities. The intermediary facilitating the offering will be identified in such offering’s documentation.

All related securities activity is conducted by OpenDeal Broker LLC a registered broker-dealer, Member of FINRA and SiPC, an affiliate of OpenDeal Inc. and OpenDeal Portal LLC, located at 149 5th Avenue, 10th Floor, New York, NY 10010. Please check our background on FINRA’s BrokerCheck.

Certain pages discussing the mechanics and providing educational materials regarding regulation crowdfunding offerings may refer to OpenDeal Broker LLC and OpenDeal Portal LLC collectively as “Republic”, solely for explanatory purposes.

Neither OpenDeal Inc., OpenDeal Portal LLC nor OpenDeal Broker LLC make investment recommendations and no communication, through this Site, or in any other medium, should be construed as a recommendation for any security offered on or off this investment platform. Investment opportunities posted on this Site are private placements of securities that are not publicly traded, involve a high degree of risk, may lose value including the total loss of invested capital, are subject to holding period requirements and are intended for investors who do not need a liquid investment. Past performance is not indicative of future results. Investors must be able to afford the loss of their entire investment. Only qualified investors, who understand the risks of early-stage investment and who meet the Republic's investment criteria may invest. Investors may be restricted to only Accredited Investors or non-U.S. persons, to invest in offerings hosted by OpenDeal Broker. Neither OpenDeal Inc., OpenDeal Portal LLC nor OpenDeal Broker LLC, nor any of their officers, directors, agents and employees make any warranty, express or implied, of any kind whatsoever related to the adequacy, accuracy or completeness of any information on this Site or the use of information on this site. Offers to sell securities can only be made through official offering documents that contain important information about the investment and the issuers, including risks. Investors should carefully read the offering documents. Investors should conduct their own due diligence and are encouraged to consult with their tax, legal and financial advisors.

By accessing the Site and any pages thereof, you agree to be bound by the Terms of Use and Privacy Policy. Please also see OpenDeal Broker’s Business Continuity Plan and Additional Risk Disclosures. All issuers offering securities under regulation crowdfunding as hosted by OpenDeal Portal LLC are listed on the All Companies Page. The inclusion or exclusion of an issuer on the Platform Page and/or Republic’s Homepage, which includes offerings conducted under regulation crowdfunding as well as other exemptions from registration, is not based upon any endorsement or recommendation by OpenDeal Inc, OpenDeal Portal LLC, or OpenDeal Broker LLC, nor any of their affiliates, officers, directors, agents, and employees. Rather, issuers of securities may, in their sole discretion, opt-out of being listed on the Platform Page and Homepage.

Investors should verify any issuer information they consider important before making an investment.

Investments in private companies are particularly risky and may result in total loss of invested capital. Past performance of a security or a company does not guarantee future results or returns. Only investors who understand the risks of early stage investment and who meet the Republic's investment criteria may invest.

Neither OpenDeal Inc., OpenDeal Portal LLC nor OpenDeal Broker LLC verify information provided by companies on this Site and makes no assurance as to the completeness or accuracy of any such information. Additional information about companies fundraising on the Site can be found by searching the EDGAR database, or the offering documentation located on the Site when the offering does not require an EDGAR filing.

To help the government fight the funding of terrorism and money laundering activities, Federal law requires all financial institutions to obtain, verify, and record information that identifies each person who opens an account. Therefore, when you use the Services we will ask for your name, address, date of birth, and other information that will allow us to identify you. We may also ask to see your driver's license, passport or other identifying documents.

Republic and its affiliates are not and do not operate or act as a bank. Certain banking services are provided by BitGo Trust Company, a South Dakota-chartered trust company and registered money services business. BitGo Trust Company is not an FDIC member. Digital (crypto) assets and investment products are not insured by the FDIC, may lose value, and are not deposits or other obligations of BitGo Trust Company and are not guaranteed by BitGo Trust Company. Terms and conditions apply.

Invest in startups using your credit card
You can invest using your credit card

Made in SF/NYC